You can buy property in Hawaii from Hong Kong without being a citizen or green card holder of the U.S. You first need to define your budget and select suitable locations. Then, compare property types and mortgage options that are available. The real estate agent in Hawaii can help find suitable properties and arrange virtual tours.
Next, you need to consider documents, tax, insurance, and other local restrictions. After you choose a property, submit your offer and sign purchase agreement. Escrow company can help you manage your deposits, conduct title search, prepare documents, and facilitate closing. Also, you can check out this guide on Buying Real Estate in Hawaii as a Foreign National.
America Mortgages will help you to select suitable U.S. mortgage products for purchasing property in Hawaii from Hong Kong. Contact America Mortgages right now to get more information regarding financing options.
Can Hong Kong Residents Legally Buy Property in Hawaii?
Yes, residents of Hong Kong are legally allowed to buy private residences in Hawaii without being a citizen of the U.S., obtaining a green card, or permanent residency status. Buyers who are foreign nationals can look into eligible homes, condominiums, townhomes, and investment properties on the islands. There are certain government land projects with their own criteria for buyers.
| Property Type | Foreign Buyer Eligibility | Important Consideration |
| Single-Family Homes | Generally eligible | Check ownership rights and property restrictions. |
| Condominiums | Generally eligible | Review association rules and ownership documents. |
| Townhouses | Generally eligible | Confirm fee-simple or leasehold ownership. |
| Luxury Properties | Generally eligible | Consider insurance, taxes, and maintenance expenses. |
| Vacant Land | Generally eligible for eligible private land | Check zoning and development restrictions. |
The first thing to note is fee simple and leasehold ownership. Fee simple means that one has ownership of the land and the property on it. Leasehold is when one gets use of the land and property only for a particular period. Hence, check the number of years left, the ground rent, and conditions of renewing leasehold before buying.
There are some other criteria for buyers of Hawaiian Homelands. The applicants must be of age 18 years or older. Besides, one should be a descendant of Native Hawaiians by at least 50%. This type of homestead is different from buying ordinary private property.
A Hawaii lawyer can be consulted prior to making any offer to verify any ownership rights, titles and restrictions that may be involved. This will give the Hong Kong purchasers a better understanding of their legal standing in the situation.
What Steps Should Hong Kong Buyers Follow to Buy Property in Hawaii?
Steps to buy a property in Hawaii from Hong Kong involves setting up a budget, researching into the market, and applying for mortgage finance. After that, choose a property and conduct inspections. Then, place your offer, sign the purchase agreement, get ready for escrow and finally register your ownership.
Setting Your Property Budget
Find out how much you can afford to pay for your Hawaii property. It should include down payment, monthly payments, insurance, taxes and closing costs. Don’t forget about the exchange rate HKD to USD.
Researching The Property Market of Hawaii
Do your research and explore various islands, neighborhoods and communities before choosing the location. Pay attention to the prices of property, demand for rentals, accessibility and amenities of the area. In addition, find out if the property is fee-simple or leasehold.
Mortgage Pre-Approval
Contact the mortgage lenders providing foreign national mortgage program prior to making an offer. Prepare your passport, earnings documentation, bank statements and other financial information.
Engage a Local Real Estate Agent
Work with a locally licensed agent with experience in buying property from overseas clients. The agent will screen appropriate properties, conduct virtual tours, explain the current market conditions, and negotiate the terms of the sale. An independent lawyer will assist in analyzing the structure of the deal.
Conduct an Independent Inspection and Examination of Papers
An independent inspection of the property should be performed prior to purchasing. Examine the title report, disclosures by the seller, condominium papers, insurance information, and any restrictions that may apply.
Make an Offer and Sign the Agreement
Ask the agent to prepare an offer taking into account your budget and terms of purchase. Make sure to include the necessary contingencies. Both sides will sign the purchase agreement once the seller accepts the offer.
Complete Escrow and Wire Your Money
An escrow company will handle your deposits, title check, closing paperwork, and financial issues. Transfer your final money via official banking procedures. Make sure to double-check the wiring information.
Closing of the Deal and Recording of the Deed
Look at the settlement statement and sign the documents needed for closing. Once your lender meets all requirements, it will release funds to pay off the mortgage. The deed is recorded with Hawaii Bureau of Conveyances or whatever recording agency is used.
The Hawaii property purchase transaction involves the use of escrow as well as the recording of deeds. The Hawaii Bureau of Conveyances maintains all the property records in Hawaii. As you are buying from another country, work with your agent, lender, and escrow officer during the process of closing.
What Financing Options Are Available for Hong Kong Property Buyers?
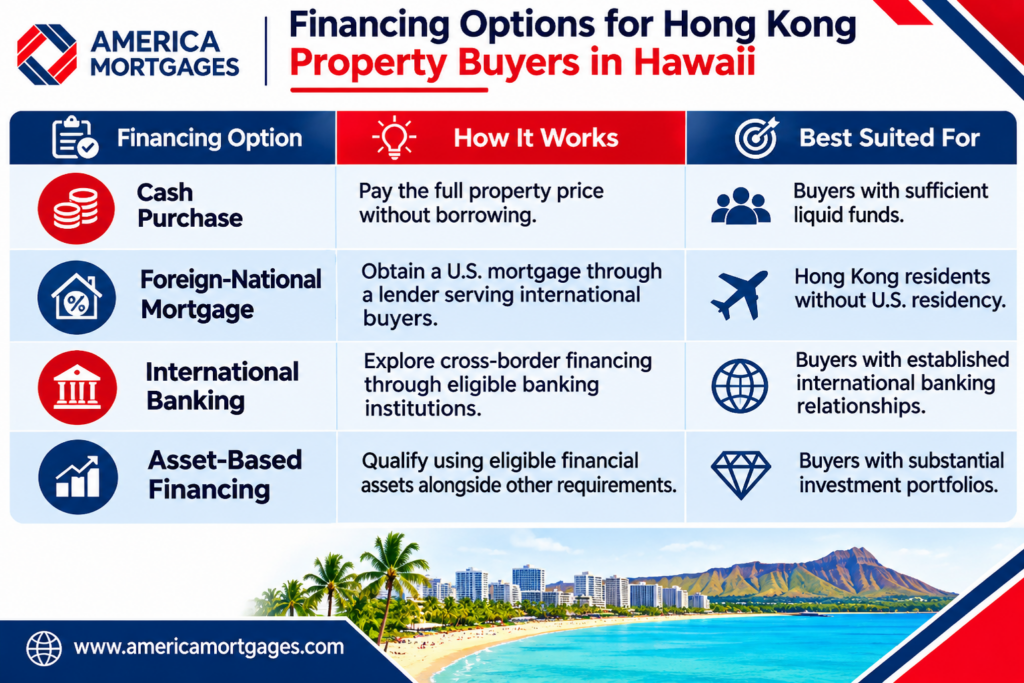
Hong Kong residents can finance Hawaii property through cash buying, foreign-national mortgages, and certain international financial schemes. Choosing the best scheme is based on your income, savings, credit profile, and type of property. There are some U.S. lenders who consider foreign income and bank statements for foreign-national mortgages.
Example: Calculate Your Required Down Payment
If you decide to buy Hawaii property with a cost of $800,000, and your lender will approve a mortgage amounting to 70% of its price.
| Financial Details | Amount |
| Property Purchase Price | $800,000 |
| Down Payment (30%) | $240,000 |
| Mortgage Amount (70%) | $560,000 |
You will have to put up $240,000 as down payment, excluding the costs of closing the deal. Actual financing percentages depend on lender approval and property eligibility.
You will need to gather your Hong Kong bank statements, proof of employment, income documentation, and identification documents prior to application. Your lender may also require your international credit report, along with the source of your down payment. You can check out this guide to US mortgages for foreigners from other countries.
Since your income might be paid in HKD, take exchange rate fluctuations into account when thinking about your repayment plan. Additionally, you should compare interest rates, repayment periods, mortgage fees, and foreign currency exchange fees. An expert on mortgages can assist you with your assessment of the available mortgage programs.
What Taxes and Additional Costs Should Hong Kong Buyers Expect?
Hong Kong buyers looking to buy properties in Hawaii should budget for property taxes, insurance premiums, closing costs, and maintenance costs. Additionally, there could be U.S. taxes that would have to be paid in the event of rent income and resale of the property.
Aside from the cost of purchasing the property, some other significant costs include:
- Property Taxes: Rates of property taxes vary depending on location and classification of property. For instance, the rate of residential properties in Honolulu for the fiscal year 2026-2027 is $3.50 for every $1,000 of net taxable value. There could be different classifications of investment properties.
- Closing Costs: Escrow fees, title services, recording fees, lender fees, and prepaid costs can all be incurred by buyers. Exact costs vary based on the cost of the house and mode of financing.
- Homeowner’s Insurance: The premium rates of home insurance vary based on the location of the property, its construction, the kind of coverage required and risks of natural disasters. The location near the shore will require extra insurance considerations.
- Condo Fees: Condo owners normally pay monthly association fees. These are for covering shared amenities, building maintenance and costs of common areas.
- Rental Income Taxes: Rental income from properties in Hawaii can result in U.S. federal and state tax liabilities. Qualified foreign non-resident owners can use certain expenses to offset the rental income tax liabilities.
- FIRPTA Withholding: FIRPTA withholding tax is levied at a 15% rate on any foreigner disposing of U.S. property.
- Withholding on HARPTA: The state of Hawaii normally requires a withholding of 7.25% based on the gain from the sale of property in the state by a seller who is a nonresident of Hawaii. This is a tax withholding requirement and does not necessarily reflect the total taxes owed.
These costs can depend upon the location, value, and intended use of your property. So you need to ask for a cost estimate before you enter into the purchase contract. You can get assistance from a Hawaii real estate professional and a U.S. tax advisor in making a budget.
Case Study: How America Mortgages Helped a Family Purchase a $9.5 Million Hawaii Estate
The Californian couple wished to move to Wailea, Maui and buy a $9.5 million ocean front property. The couple’s financing application, however, presented difficulties because of complicated income sources. Their income included retirement distribution, rents, and board compensation. It was difficult for conventional banks to evaluate their financial status.
America Mortgages provided a solution by providing asset based financing services. America Mortgages provided $6 million bridge financing at 63% loan to value (LTV) on the Hawaii property. The America Mortgages team was able to complete the funding in 18 working days. Meanwhile, the couple listed their $6.8 million Tiburon house and sold it in 52 days. America Mortgages then provided permanent DSCR financing from the rents generated from their California investment portfolio.
This is an example of the way America Mortgages helps purchasers cope with complicated income criteria to buy valuable properties in Hawaii. This transaction has been conducted with California residents and not with Hong Kong purchasers.
Explore Your Hawaii Mortgage Options with America Mortgages
Buying real estate in Hawaii from Hong Kong means you need to have the correct mortgage solutions. America Mortgages assists foreign buyers in investigating appropriate U.S. mortgage programs from abroad. With access to 150+ mortgage programs from various lenders in all 50 states, their professionals assist you in evaluating your financial profile, qualifying criteria, and the mortgage process from start to finish.
Regardless of whether you want to buy a vacation home, condo, or rental property, America Mortgages is capable of guiding you in exploring financing options. Their professionals understand the demands of foreign nationals when it comes to mortgages, especially when you cannot visit the U.S.
Interested in mortgaging your Hawaii property? Contact America Mortgages now at +1 (845) 583-0830. Alternatively, you can email [email protected] or visit America Mortgages to discuss your mortgage requirements and explore available options.
FAQs
Q1: Can I get a U.S. mortgage from a Hong Kong bank account?
Yes, it is possible to apply for a U.S. mortgage even if you keep an account in Hong Kong. Lenders consider your financial stability, your income, and the amount of money at your disposal. Some lenders accept foreign bank statements as a means of verifying funds.
Q2: What credit score do foreign buyers need to qualify for a Hawaii mortgage?
Foreign buyers do not need to have an established credit rating in the U.S. However, some loan providers check international credit reports, payment history, and existing loans. Certain foreign national loan programs offer alternative qualification criteria. The conditions differ from one lender to another.
Q3: Can I use my Hong Kong income to qualify for a U.S. home loan?
Yes, many lenders consider income earned in Hong Kong when assessing mortgage applications. One might have to furnish job letters, salary slips, tax documents, and bank statements. Besides, the lender will look at the currency exchange and liabilities among other factors.
Q4: Are Hawaii rental properties eligible for foreign-national mortgage financing?
Yes, certain Hawaii rental properties qualify for foreign-national mortgage financing. However, the eligibility will be determined by a number of factors like type of property, occupancy intentions, and criteria set by the lender. Investors are expected to make higher down payments.
Q5: How do I transfer a large down payment from Hong Kong to the United States?
You have the option of transferring the down payment by using either an international bank wire or an approved currency transfer service. First, compare exchange rates and transaction fees. Next, confirm the escrow instructions separately. Maintain records such as bank statements and transfer documents.
Share this article
Ready to get started?
Speak with our U.S. mortgage specialists today and discover your options.
Schedule a call