Yes, U.S. expats can buy an Airbnb property in the USA. American citizenship ensures that one can own properties from abroad. But before purchasing the property, issues such as financing, rentals, taxes, insurance, and management must be considered.
Properties can generate income as well as create property equity in the long run through short-term rentals. But the outcome will depend on the occupancy rate, nightly fees, operational costs, and local demand. Different rules apply to different cities and counties.
Financing must also be considered before making an offer. Foreign profits may need further evidence in the underwriting process. Buyers should check out the U.S. mortgages for U.S. expats guide for more details on the financing issues when living abroad. Local management is also crucial. A good team will deal with the guests, maintenance, and emergencies.
America Mortgages is the right source for expats who want to know about the financing possibilities for eligible investment property.
What Are the Requirements for U.S. Expats Buying an Airbnb?
U.S. expats require adequate financing, confirmed earnings, assets, and also a valid property. Expats should also be sure of local laws on short-term rentals prior to purchasing a property. These vary according to lenders and location. Thus, prospective buyers should consider mortgage terms and short-term rental policies before making an Airbnb purchase.
| Requirement | What to review |
| Income | Employment, business, or other qualifying earnings |
| Assets | Down payment, closing costs, and reserves |
| Credit | Credit history and lender requirements |
| Property | Location, condition, and rental potential |
| Rental approval | Permits, zoning, and local restrictions |
| Insurance | Coverage for short-term rental activity |
| Management | Local support for guests and maintenance |
Expats should ensure that they have all their financial papers ready before applying for a mortgage. These include income statements, tax papers, bank statements, and even asset confirmation. Foreign income might also warrant extra scrutiny. Thus, having these papers ready could ease the process.
According to IRS Publication 54, U.S. expats are normally bound by U.S. taxation laws. Thus, expats need to think about their tax liabilities before buying an Airbnb investment property. Rental income, expenses, and foreign residency can affect reporting requirements.
How Can U.S. Expats Finance an Airbnb Property?
U.S. expats are able to obtain financing for their Airbnb investment by using the appropriate programs of mortgage for investment property. Lenders will consider income, creditworthiness, assets, cash reserves, and specifics of the property. In the case of foreign income, there might be further paperwork required. This is why one should study all available options before applying for a loan.
There are several aspects that could affect the process of financing:
- Foreign income: Additional documents may be required.
- Credit history: Good credit record from the United States would be helpful.
- Down payment: More cash is usually needed to buy investment property.
- Cash reserves: Additional money might be required after closing.
- Property eligibility: The house needs to satisfy the conditions of the lender.
- Rental income: Specific criteria for expected income from rentals.
- Documentation: Additional paperwork might be required because of the international origin of some documents.
Fannie Mae’s guidelines enable some forms of short-term rental income to help qualify for the mortgage. The property must satisfy all relevant eligibility criteria. Banks can assess rental records and determine qualifying income through prescribed techniques. Hence, the buyer needs to ensure that their Airbnb income qualifies them for financing before buying.
Is an Airbnb Property Profitable for U.S. Expats?
Yes, an Airbnb can be profitable for U.S. expatriates under certain conditions. However, revenue is not the only determinant of return on investment. Prospective owners must consider demand levels and associated costs in relation to monthly rent and other expenses before buying a property.
Rental Demand
High rental demand can ensure regular bookings. Proximity to entertainment venues, the beach, downtown, and events can bring more visitors to the place. Nevertheless, demand might vary seasonally. That is why buyers need to investigate local occupancy trends before calculating annual earnings.
Nightly Rates
A high nightly rate can bring in more revenue. Nonetheless, a listing’s price should be consistent with the local market price. Competitive listings can show the average price per night for a comparable listing. Dynamic pricing can help owners manage prices depending on peak periods.
Operating Expenses
Profit is influenced not only by booking revenues. Utilities, cleaning, maintenance, insurance, tax, platform commission, and property management fees can affect cash flow. That is why prospective investors need to take them into account while calculating profits.
Performance Seasonality
There are some areas that show very strong peaks followed by a slower period. Holiday seasons, weather, and events in the region can impact the bookings. The investment should be financially feasible even in slow periods. In this way, it could limit the dependency on overly positive revenue expectations.
Property Location
Location has significant importance for the short-term performance of the investment. Nearby points of interest could help attract more clients and charge higher prices. However, one has to consider local renting regulations as well. Having a profitable market is not helpful unless the property can work there legally.
Management Expenses
The owners of the properties who live in the U.S. but abroad would need the help of the locals. The professionals will help with taking care of the guests, cleaning, repairs, and any emergencies that might occur. Such expenses will lower the revenue but will increase the reliability.
The investor needs to compare expected income against the total cost of owning. A short-term rental investment guide for property owners may assist in explaining such things as occupancy, rates per night, and operational costs.
In general, profitability will depend on the particular property and the location. Having a good location is not enough to ensure profitability. Proper projections will help U.S. expats to make a better-informed investment choice.
What Should U.S. Expats Check Before Buying an Airbnb?
U.S. expats should check the rental regulations, restrictions, insurance, operating costs, and management options prior to purchasing an Airbnb. Other aspects that require assessment include guest demand and the conditions of the location. A thorough analysis would help determine any possible limitations and additional costs ahead of time.
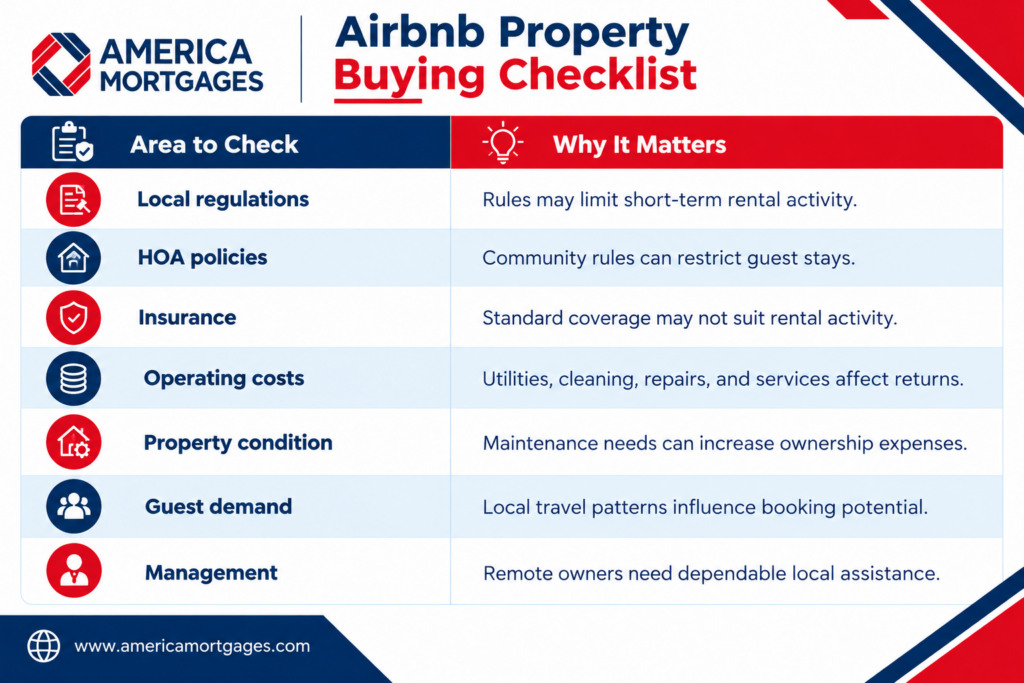
First, analyze the surrounding area and rental market for the property. Analyze the availability of amenities, transportation, as well as other Airbnb options in the neighborhood. Seasonality is also important. A property would generate different results in holiday seasons, in high and low seasons. An analysis of vacation home investments could help the buyer make more realistic estimates.
Secondly, think about the operation of the property abroad. Define the processes regarding communication with guests, cleaning and maintenance services, as well as emergency procedures. In addition, be ready for any unexpected expenses for repairs. A reliable local contact person would come in handy.
Case Study: U.S. Expat Refinances a Florida Rental From Singapore
America Mortgages helped an American expatriate teacher residing in Singapore to refinance his rental property in Tampa, Florida. The transaction was designed keeping in mind the foreign scenario of the borrower along with the rental income from the property. Thus, the client got the opportunity to go ahead with the refinancing process despite the fact that there was no typical employment scenario in the U.S.
This case study demonstrates the benefits that come with expat financing as well. America Mortgages facilitated the refinance process through the rental income approach.
Start Financing Your U.S. Airbnb Property With America Mortgages
Financing the Airbnb property becomes relatively easy with a good loan structure. U.S. expatriates may have specific requirements concerning income and documentation. Hence, choosing the right mortgage lender can make the entire process easier. It will also help you determine what financing options are available for your investment.
Before applying for the loan, gather all your income documents, asset statement, credit information, and details about your property. In addition, check your estimated rental income and expenses. Doing this will assist lenders to consider your application easier. You will also be able to see more clearly what investment you can make.
Are you ready to consider financing options? America Mortgages can assist you to find the most appropriate financing options for your U.S. Airbnb property. You can contact our representatives by calling +1 (845) 583-0830 or sending an e-mail to [email protected].
FAQs
Q1: Can a U.S. Citizen Living Abroad Buy an Investment Property?
Yes, a U.S. citizen living abroad is allowed to invest in a property in the U.S. Living abroad does not hinder the process of owning a property. Issues such as financing, documentation of earnings, taxation, insurances, and property laws may come into play.
Q2: Can I Airbnb My Second Home in the U.S.?
Yes, you may be able to rent out your second house in the U.S. via Airbnb, depending on local regulations. Be sure to examine the rules for short-term rentals, including zoning, homeowners association, insurance, and tax regulations.
Q3: Do I Pay Taxes on Airbnb Income in the U.S. If I Live Abroad?
Yes, Airbnb income earned by U.S. citizens while living abroad may be subject to U.S. taxes. Depending on rental income, expenses, location, use, and tax laws, your situation will vary. Consulting a professional is recommended for further clarification.
Q4: Can I Get a Mortgage in the U.S. With Foreign Income?
Yes, expats have the possibility to obtain mortgages in the USA on the basis of their foreign earnings. The lenders can analyze employment history, tax records, bank account statements, and exchange rate stability. Each mortgage program has its own requirements.
Q5: What Credit Score Does an Expat Need to Buy U.S. Property?
An expat will be qualified by having a credit score of 620. Higher scores mean better chances of being approved and getting good deals. In addition, factors such as earning capacity abroad, outstanding debts, assets, savings, and properties will determine mortgage qualification.
Share this article
Ready to get started?
Speak with our U.S. mortgage specialists today and discover your options.
Schedule a call