Buying property in Arizona without a US credit score is possible with either cash purchases or special mortgage programs. There are some lenders who take into account alternative credit history, foreign earnings, bank statements or the performance of the rental property. Nevertheless, you have to consider your financial situation and the lender’s requirements.
Before choosing your property, compare different financing opportunities and determine the amount of the down payment that you have to pay. Be ready to provide evidence about your earnings, identity, bank statements, as well as availability of the money. The international buyers can also look for mortgage programs for foreigners.
The team at America Mortgages can advise you on mortgage options which suit your case. You may contact the company regarding your property purchase in Arizona.
What Financing Options Are Available Without a US Credit Score?
There are various financing options available for you that do not require a US credit score, such as alternative credit mortgages, ITIN loans, foreign national mortgages, DSCR loans, and purchasing with cash. This depends on various factors, such as your citizenship and finances.
- Alternative credit mortgage: Some financial institutions allow payments such as rents or utilities or other payments to be used as evidence of creditworthiness. This is an option that will work for those who have little to no US credit record.
- ITIN mortgage: Those who fit the requirements for this kind of mortgage can use their ITIN number instead of the social security number.
- Foreign national mortgage: There are some financial institutions that will look at overseas income, assets, and financial information of foreign nationals. This will be a good option for foreigners who want to finance American real estate.
- DSCR loan: This loan looks at whether the rentals earned from the property can cover the debt service. This will work well for investment purchases.
- Cash purchase: Those who have cash available for the purchase do not need to apply for a mortgage but need to follow all the necessary procedures.
The need for alternative financing is shown by some research findings. For instance, the U.S. Government Accountability Office (GAO) published a report that revealed that less than 0.1% of the mortgages bought by Fannie Mae and Freddie Mac from 2016 to 2020 had borrowers without credit scores. This report was aimed at assessing the possibility of using alternative financial data in assessing such applicants who have no credit history. View more about the GAO mortgage lending report.
In the case of Arizona residents, the strategy would be to compare the lenders who take applications from individuals who have no credit history in the US. The interest rates, down payments, closing costs, reserves, and financial documents should be confirmed from the lender.
What Steps Should You Follow to Purchase Property in Arizona Without US Credit History?
You can purchase property in Arizona without US credit history by finding a suitable lender, preparing financial documents, and meeting the property’s purchase requirements. First, confirm your eligibility and budget. Then, compare financing offers before making an offer on a home.
| Step | What to do | Why it matters |
| Assess eligibility | Confirm your residency status and intended property use. | Helps identify suitable loan programs. |
| Gather documents | Prepare identification, bank statements, income records, and proof of funds. | Supports financial verification. |
| Compare lenders | Request written quotes and review loan conditions. | Helps you understand borrowing costs. |
| Select a property | Review location, condition, insurance, and potential expenses. | Reduces unexpected costs. |
| Submit an offer | Include suitable financing and inspection protections. | Helps safeguard your interests. |
| Complete closing | Review the title, final loan terms, and closing documents. | Confirms the details before ownership transfers. |
After finding a good lender, ask whether the lender takes international income or other sources of money. The rules differ depending on the lender, so get this information in writing before sending any money for an application. In addition, find out the closing process time and limitations concerning the property type.
Researching the property in question is just as crucial while selecting the best option. First, calculate your budget and other costs and look into your future intentions regarding the real estate. It is also helpful to learn more about buying real estate in Arizona as a non-resident.
What Documents and Costs Should You Prepare Before Buying?
Before buying property in Arizona without a credit history in the US, make sure you have identification, financial documentation, proof of funds, and a budget. You will also need to calculate the amount of down payment and closing costs and all other extra charges that might apply.
Important Identification Documentation
Make sure to have an appropriate passport or any other type of identification. Depending on your situation, the lender may require your Social Security number or Individual Taxpayer Identification Number (ITIN). The non-US citizen might be required to provide information about their visa.
Documentation Related to Income and Finances
Make sure to provide recent bank statements, work documentation, tax returns, and asset documentation. If you receive income outside the US, find out whether translation of these documents is necessary or not.
Proof of Down Payment and Available Funds
It is important to prove that you have sufficient funds for the down payment and all other expenses related to the purchase. Lenders can also ask you to prove where the funds came from.
Mortgage Application and Property Information
Compile your mortgage application and property information as required. Upon selecting a suitable house, organize for an inspection and examination of the purchase contract. The mortgage provider will also need an appraisal and title examination to consider lending money.
Determine Your Initial Cost Estimate
Assume that the price of the property is $300,000 and that the down payment is 25%. The initial cost estimate would be:
| Expense | Estimated amount |
| Property price | $300,000 |
| Down payment (25%) | $75,000 |
| Closing costs (3%, estimated) | $9,000 |
| Total upfront costs | $84,000 |
| Remaining mortgage amount | $225,000 |
The above are examples only and not from your lender. Depending on the loan program, your property, and how the deal is structured, the real expenses will vary. Expenses other than those listed above could include inspection fees, insurance costs, taxes paid in advance, and the necessary reserves.
In order to prepare an accurate budget, ask your lender for an estimate of the total cost. This will allow you to know how much money you have to spend.
What Do Arizona Property Market Trends Reveal for Buyers Without US Credit?
The trends in the Arizona property market can assist buyers with no credit history in America to make plans in terms of budgeting and finance, compare various areas, and apply for mortgage loans. However, trends in the property market cannot ensure that one will get a mortgage.
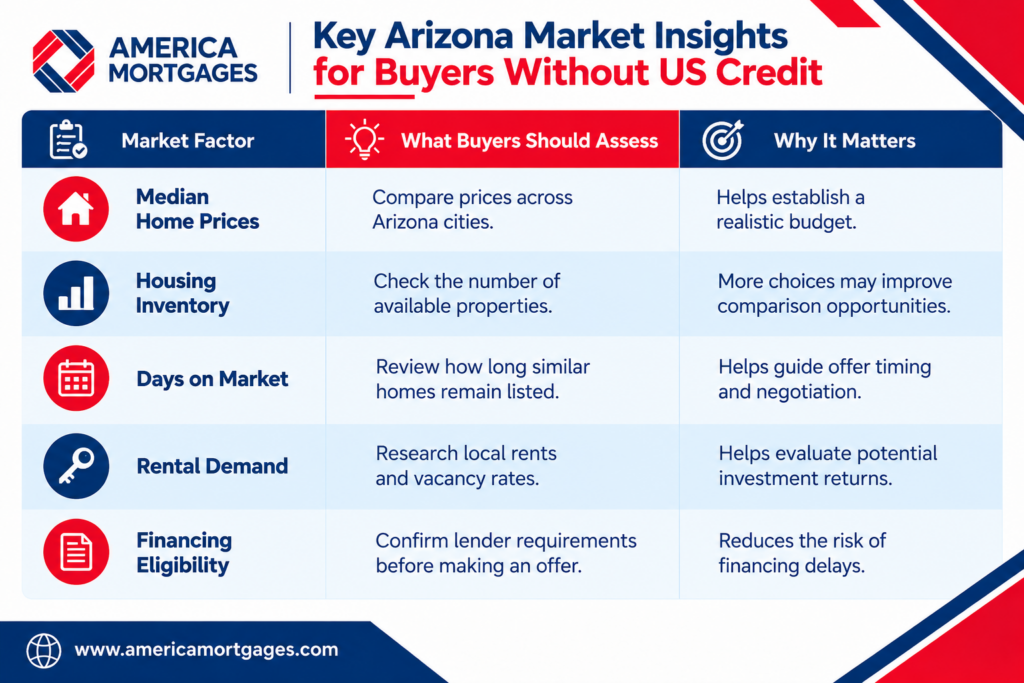
Based on the October 2026 STAT report from the ARMLS, Arizona had a median home price of $450,000 in September 2026, which was at the same level as the previous year. The housing inventory stood at 4.45 months, thus providing useful information to help buyers compare homes.
Such information can assist buyers to gauge their budgets and compare different local housing markets. However, buyers who do not have credit in the US should verify their mortgage eligibility before putting in an offer.
Case Study: Financing an Arizona Rental Property With Overseas Income
America Mortgages helped an American citizen living in Hong Kong to refinance his four-bedroom rented property located in Tempe, Arizona. The borrower was earning from abroad and did not have any traditional income documents such as W-2 document and standard payslips for income certification. This case is a classic example of how mortgage financing works for borrowers with unusual income documents.
The lender provided an official mortgage offer in ten working days, after which the refinancing process was completed. The borrower succeeded in obtaining a lower interest rate. The main importance of this case is that buyers of properties located in Arizona must know whether lenders recognize overseas income and other types of income documentation. However, this case deals with an American expatriate refinancing his property rather than buying one.
Start Your Arizona Property Purchase With America Mortgages
Buying property in Arizona when you have no US credit score demands a lot of planning. Knowing your financing, down payment, and what your lender expects may assist in simplifying the procedure. With proper planning, you will be able to feel more confident during the purchase process.
Before selecting the property, you should examine your finances and compare mortgage programs that might suit you. It will depend on your budget, income level, and investment objectives.
Ready to see what options are available to you? Our experts at America Mortgages can provide you with information on possible mortgage options for you. Please contact us by calling +1 (845) 583-0830 or emailing [email protected].
FAQs
Q1: Can I buy a house in Arizona as a foreigner?
Yes, foreigners are eligible to buy property in Arizona despite not being US citizens. However, financing eligibility depends on the lender’s requirements. Before buying, review ownership rules, closing costs, and applicable tax obligations to avoid unexpected expenses.
Q2: Do Arizona lenders accept foreign income for a mortgage?
Yes, some Arizona lenders consider foreign income in evaluating their application. They require employment letters, tax documents, bank statements, and currency exchange documents. But it all depends on the program under which the loan is sought.
Q3: Can I use an international bank statement to buy property in Arizona?
Yes, international bank statements can indeed be used for purchasing property in Arizona. International bank statements can prove your available funds and savings. However, banks could ask for certified translation and additional paperwork to confirm the source of your funds.
Q4: Do I have to pay cash to buy US property without credit history?
No, paying cash is not your only option when buying US property without credit history. Certain lenders offer specialized mortgage programs. They may evaluate assets, rental income, alternative credit records, and down payment amounts instead.
Q5: What taxes do foreign investors pay on Arizona rental properties?
Foreign investors will need to pay tax on rental income at the federal level and state level in Arizona. Typically, there will be deduction allowances for eligible costs. Finally, FIRPTA withholding needs to be considered in some cases of property sales.
Share this article
Ready to get started?
Speak with our U.S. mortgage specialists today and discover your options.
Schedule a call