
The U.S. Expat Mortgage Problem
As an American living abroad, you might have encountered some difficulties securing a mortgage back home in the U.S.
“We can’t use your foreign income.”
“Your employer needs to complete this verification form.”
“We need a U.S. W-2.”
“You need a U.S. address.”
“Your credit history is too thin.”
“We can’t approve you because you live overseas.”
“You don’t fit our guidelines.”
However, just because you live abroad doesn’t mean you don’t qualify for financing. You are still an American citizen who pays taxes to the U.S. government. In addition, you might earn a good salary and possess many assets. Finally, you might have a good credit score.
This could have to do with the lender’s infrastructure and not with your ability to qualify financially. There are some lenders that are not geared towards expats. This article will give an understanding of how U.S. underwriting considers foreign income and foreign credit. Foreign taxes and loan products, including those meant for expats and Green Card holders will be considered as well.
This guide will also cover topics like DTI, DSCR, cash-out refinance and portfolio building remotely. It will consider how bridge financing and credit building can work in your plans. There is also the issue of repatriation planning. The case studies used in the course are made up of composite or hypothetical scenarios. They do not refer to real clients or actual deals.
Contents
- Why Do Banks and Generalist Lenders Struggle With Expat Files?
- Fannie Mae Guidelines and the Reality of Expat Financing
- Why Foreign-Earned Income Creates Documentation Challenges
- U.S. Taxes, the Foreign Earned Income Exclusion, and Your Mortgage
- Maintaining Your U.S. Credit Footprint While Abroad
- Lost Your U.S. Footprint? The Path Back
- Green Card Holders Living Overseas
- Mortgage Options at a Glance
- Debt-to-Income Ratio, Explained by Property Type
- DSCR Investment Loans: How Qualification Works
- Buying a Home, Vacation Home, or Investment Property Overseas
- Already Own U.S. Real Estate? Cash-Out Refinancing and Equity Recycling
- Building a Portfolio: Is There a Limit?
- Moving Back to the U.S.: Why Timing Matters
- The U.S. Expat Property-Buying Process, Step by Step
- Real Estate Bridge Loans
- Common Reasons Expat Mortgages Get Declined
- Why Specialization Matters
- The Expat Mortgage Documentation Checklist
- The U.S. Expat Mortgage Decision Tree
- Where U.S. Expats Live — and Why U.S. Real Estate Still Wins
- Buying a Home for Your Child’s College Years
- Why this can be one of the more persuasive decisions in this entire guide
- Frequently Asked Questions
- About This Guide
1. Why Do Banks and Generalist Lenders Struggle With Expat Files?
Most major banks and retail lenders in the U.S. use a standardized lending system. Such a system works well for regular domestic borrowers.
The domestic borrower has an American employer and W-2 income. They also have American pay slips and bank accounts. The file contains a US address and credit score. Standard US tax forms are also typical. The financial profile of an expat is typically different.
| Typical Domestic Borrower | Typical U.S. Expat Borrower |
| U.S. employer, U.S. W-2 | Foreign employer, foreign payslip |
| U.S. bank accounts | Foreign bank accounts, foreign currency |
| U.S. residential address | Foreign residential address |
| Continuously active U.S. credit | U.S. credit history, possibly dormant |
| Standard U.S. tax return | U.S. tax return with foreign income, possibly FEIE |
However, this does not always imply that the finances of the expat are weaker. They might have higher income, more savings, or experience. Nevertheless, the unusual documentation creates some underwriting problems.
An important distinction
The mortgage might be approved by agency standards but be hard to process for some lenders. Banks might have more strict internal requirements. These requirements may include foreign income, foreign addresses, countries, and work. When the lender says, “we don’t do expat loans,” it means that such financing is not in line with their lending policies. It doesn’t mean that other lenders cannot provide funding.
ILLUSTRATIVE EXAMPLE
David Whitfield — Munich, Germany
David, an American software engineer, had lived and worked in Munich for six years and wanted to buy a rental property in Austin. His hometown bank declined within a week, citing his foreign address and lack of a U.S. W-2.
The income itself wasn’t the problem — David earned a strong, stable salary from a well-known German employer. The bank’s system simply wasn’t built to process a foreign address or a foreign payslip. A lender built around this exact borrower profile was able to document the same income through his employer letter, payslips, and tax returns, and the loan closed within the program’s normal timeline.
2. Fannie Mae Guidelines and the Reality of Expat Financing
The misconception about Fannie Mae is that it has regulations that apply to foreign mortgages. That is not the case. Fannie Mae determines the guidelines for borrowers and transactions on its loans purchased through the agency process. The guidelines span a wide variety of issues. Such guidelines include borrower qualification, income, employment, credit, assets, and property. There are also guidelines for occupancy, debt, rent, refinancing, and financed properties. It is up to individual lenders whether borrowers and transactions qualify for the guidelines. Individual lenders can also impose additional internal guidelines.
Foreign income is not automatically prohibited
Foreign income according to Fannie Mae is that earned by either a foreign corporation or government. Foreign income must be in foreign currency. Foreign income earners usually require tax returns for the past two years. The foreign income should appear in such tax returns. In addition, the tax returns must be in English. The income should also be expressed in terms of US dollars.
This is not the same thing as saying that Fannie Mae does not accept expats. An expat eligible according to certain criteria is able to qualify according to those criteria. The income and documents should satisfy those criteria. Even the property should satisfy certain criteria.
3. Why Foreign-Earned Income Creates Documentation Challenges
An example of such a scenario would be that of an individual living in Singapore earning SGD 400,000 from a Singaporean company every year. His salary goes to his Singaporean bank account, and he prepares his tax returns for the U.S. every year. His employer does not give him the U.S. W-2. This is because there is absolutely no reason for doing that.
The conventional lender using the W-2 verification will find this difficult. However, this does not mean that her income is unstable. The lender will have to find other ways of verifying her income. The source of her income and whether she gets her income payments on a regular basis are among the things that the lender must consider.
What happens when the foreign employer won’t respond?
This is one of the frequent problems encountered by expatriate applicants. The multinational employer may be unable to fill out the verification form required by the U.S. lending institution. Human resources departments may also refuse to accommodate new types of inquiries. Certain firms do not even have a U.S. payroll department that can deal with such requests. Conventional lenders may regard this as a road block but specialized lenders may provide for other means of documentation. These include letters from the employer, pay slips, tax forms, and bank statements.
ILLUSTRATIVE EXAMPLE
Maria Alvarez — Dubai, U.A.E.
Maria, a marketing director for a Dubai-based multinational, wanted to refinance a Florida condo. Her employer’s HR department declined to complete her lender’s verification form — it simply wasn’t part of their process for a foreign subsidiary.
Rather than treating that as a dead end, her lender substituted an employer letter, six months of payslips, and matching bank deposits as equivalent evidence of the same income. The refinance closed without the form her original bank had insisted was mandatory.
4. U.S. Taxes, the Foreign Earned Income Exclusion, and Your Mortgage
Citizens of the U.S. as well as green card holders usually declare their worldwide income even when abroad. The citizens and green card holders should also comply with the U.S. filing system. Many citizens opt for the Foreign Earned Income Exclusion program. The program allows certain foreign-earned income to be exempt from taxation by the U.S. government. In tax year 2026, the maximum exclusion amount will be $132,900.
The critical point for mortgage borrowers:
Using the FEIE does not mean you stopped earning money — and it doesn’t mean a mortgage lender will automatically see your income the way you do.
The FEIE has the potential to significantly lower taxable income on an American tax return. That can even be the case despite earning a six-figure salary. An uninformed lender would look at the very low taxable income figure. He would then determine that there is inadequate qualifying income. A knowledgeable lender will analyze all income. This includes total foreign income, income reported for tax purposes in the U.S, any exclusions and tax credits. This will enable him to arrive at the qualifying income amount.
Continue filing tax returns in the U.S. each year despite living outside the country. The FEIE does not relieve you from filing requirements. The tax return is also important when applying for mortgages. The tax return will help the lenders confirm your income and financial records.
ILLUSTRATIVE EXAMPLE
James Coleman — Tokyo, Japan
James, an international school teacher in Tokyo, applied for a mortgage with a tax return showing almost no taxable income after claiming the FEIE on his full salary. A generalist loan officer read the $0 figure literally and declined the file for insufficient income.
A lender familiar with expat tax returns traced the return back to Form 2555, identified the excluded foreign salary, and added it back in as qualifying income — the same salary, the same return, a different reading of it. The loan was approved on a second application with a specialist lender.
5. Maintaining Your U.S. Credit Footprint While Abroad
Residing outside the country for an extended period of time is sure to lessen the U.S. credit footprint that one has developed. All this is possible even without taking any effort. Credit card companies can shut down one’s account in case of non-use. Also, the U.S. bank account can go unused. There may be no mortgage in the U.S. where one could build up payment history. One can have great finances outside of the country, but an inactive credit report within the country.
This may not become apparent in one’s daily life, but when it comes to financial needs, then it will matter. It will matter when one wants to buy or refinance property within the U.S.
A simple, low-cost safeguard
- Make sure one or two credit cards issued by an American bank stay active, regardless of your location.
- Put one of those cards on autopay for some small recurring expense.
- Have at least one account at an American bank.
- Keep checking your American credit reports.
- Save documents on your financial history in America past statements, closed accounts, etc.
You don’t have to borrow money just because you want it. All you need is to keep important financial accounts while staying overseas. This way, you can avoid having an inactivity in your financial records in America.
ILLUSTRATIVE EXAMPLE
Susan Whitmore — Sydney, Australia
After nine years in Sydney, Susan let her last two U.S. credit cards lapse from disuse — no missed payments, just no activity. When she applied to refinance her Denver rental, her credit file was too thin to score at all.
She wasn’t declined for poor credit; there was simply no current file to evaluate. Reactivating one card with a small recurring charge and waiting a few reporting cycles would have avoided the delay entirely — a lesson she now applies going forward.
6. Lost Your U.S. Footprint? The Path Back
This is actually a more frequent occurrence than many expatriates realize. An expatriate could be out of the country for fifteen years without using any U.S. credit. An expatriate may also not have a U.S. bank account that they use frequently. The expatriate could also be without a U.S. mortgage for several years. An expatriate is still a U.S. citizen but may seem like an international borrower.
This does not mean that financing is unavailable. The first mortgage will be based on different criteria from that of financing domestically. However, the criteria may vary with subsequent financing.
The two-stage strategy
An international or foreign-national-style mortgage can assist with gaining entry into the American mortgage market. The terms on such loans could possibly include some compromises. The interest rates will likely be slightly higher than those for regular mortgages. Additionally, the maximum leverage available will be slightly less. Purchase mortgages will be up to 75% LTV. Cash-out refinancing will be up to 70% LTV. Alternative credit documents will substitute for a regular American credit rating.
International mortgage → make on-time payments → re-establish U.S. credit → refinance into standard expat terms → improved rate and higher leverage.
In other words: the first loan doesn’t have to be the final loan. Financing the property at all is often the fastest practical way to rebuild the credit file that unlocks better terms down the road.
ILLUSTRATIVE EXAMPLE
Michael Tran — Hong Kong
Michael left the U.S. at 24 and spent 22 years building a career in Hong Kong. By the time he wanted to buy a retirement property in San Diego, he had no active U.S. credit file at all — on paper, he looked like a foreign national despite his U.S. passport.
He financed the purchase under foreign-national terms at 75% LTV. Eighteen months of on-time payments later, his U.S. credit file was active again, and he refinanced into standard expat terms at higher leverage and a better rate.
7. Green Card Holders Living Overseas
An individual with a Green Card who is abroad may not be eligible for some programs as one would be a citizen of the United States. Nevertheless, funding is possible. Fannie Mae allows for financing in case of lawful permanent residents through proper qualifications.
In the case of Green Card holders outside the United States, the lender will consider different things. This includes the immigration status, U.S. tax return history, and income verification. The country where the applicant resides, credit, and assets may also be considered. The kind of property and loan program are equally important.
ILLUSTRATIVE EXAMPLE
Elena Petrova — London, U.K.
Elena, a Canadian-born U.S. Green Card holder working in London, assumed she’d need U.S. citizenship to get competitive financing on a Chicago investment property. She didn’t.
Because she had filed U.S. tax returns consistently and could document her U.K. employment income, she qualified under the same expat program terms available to a U.S.-citizen borrower in her situation — her Green Card status was a documentation item, not an obstacle.
8. Mortgage Options at a Glance
The concept of expat mortgages does not exist as such. You can use several financing schemes that suit you. Your income status and creditworthiness can have a bearing on the type of mortgage you get access to. So too can your financial objectives.
| Option | Best Suited For |
| Conventional / Agency Mortgage | Borrowers with strong, well-documented U.S. income, active U.S. credit, and a conventional property and occupancy. |
| Expat / Foreign-Income Mortgage | Americans abroad with foreign employment or foreign self employment income, foreign residency, and international assets. |
| DSCR Investment Mortgage | Investment purchases qualified primarily on the property’s rental income rather than personal employment income. |
| Asset-Based / Alternative Documentation Mortgage | Borrowers with significant assets but complex or hard-to document income. |
| Portfolio Mortgage | Larger or more complex borrowers where a more customized underwriting approach is appropriate. |
| Cash-Out Refinance | Expats who already own U.S. property and want to release equity. |
| Bridge Financing | Time-sensitive acquisitions, renovations, or situations where conventional timelines don’t work — covered in Section 16. |
9. Debt-to-Income Ratio, Explained by Property Type
Debt to Income Ratio (DTI) compares debt per month to gross monthly income. The calculation is straightforward but is contingent on the use of the property.
Investment property: DSCR loans generally don’t use personal DTI at all
In cases where investment property financing through DSCR financing is applied, personal income is normally not a big part of qualification. Personal employment and DTI are also normally left out in this case. Rental income from the property is what qualifies you.
Second home or vacation home: your current housing cost plus the new payment
For property used personally, personal DTI will normally apply. The calculation takes into account your current housing cost outside the U.S. It is then converted to dollars. The other part of the calculation is the total monthly cost of the new property, which will include interest and insurance costs.
Primary residence: standard DTI applies
Buying a house as a return to the U.S. works pretty much the same as domestic underwriting. You need to qualify income first. Then take into account all monthly debt obligations including the mortgage payments on the new house.
A commonly used planning benchmark is a combined DTI at or below approximately 43% of gross income.
That figure is a useful guide, not a universal rule — actual allowable DTI varies by program and underwriting method. Agency guidelines, for instance, permit different thresholds in different circumstances (Fannie Mae’s manual-underwriting path, for example, applies its own specific thresholds separate from automated-underwriting findings). Don’t treat an online DTI calculator as a mortgage qualification.
ILLUSTRATIVE EXAMPLE
Christopher Lee — Singapore
Christopher, a finance executive in Singapore, wanted a vacation condo in Naples, Florida, to use during visits — not to rent out. Because it was a second home rather than an investment property, DSCR wasn’t the right fit; personal DTI applied instead.
His lender added his Singapore housing cost to the new Naples payment and divided by his gross income, landing at 38% — comfortably under the 43% planning benchmark, and the purchase proceeded on standard second-home terms.
10. DSCR Investment Loans: How Qualification Works
Debt service coverage ratio is abbreviated as DSCR. With a DSCR loan, emphasis is placed on the rental income of the property rather than the salary of the borrower. The major question becomes whether the rental income will be able to meet the debt servicing of the property. As far as expatriates are concerned, DSCR loans can be very helpful as far as qualifying is concerned.
The calculation itself is simple:
DSCR = Monthly Qualifying Rental Income ÷ Monthly Debt Service (principal, interest, taxes, insurance, and HOA dues where applicable)
A ratio above 1.00 usually indicates that the income from rentals is sufficient to meet the payments of interest and principal. The goal of many programs is a DSCR of 1.00 or better. Good pricing may be obtained at the 1.20-1.25 level and above. Programs with particular emphasis may consider a DSCR of 1.00 or lower. Some programs may accept a ratio of 0.75 or even lower.
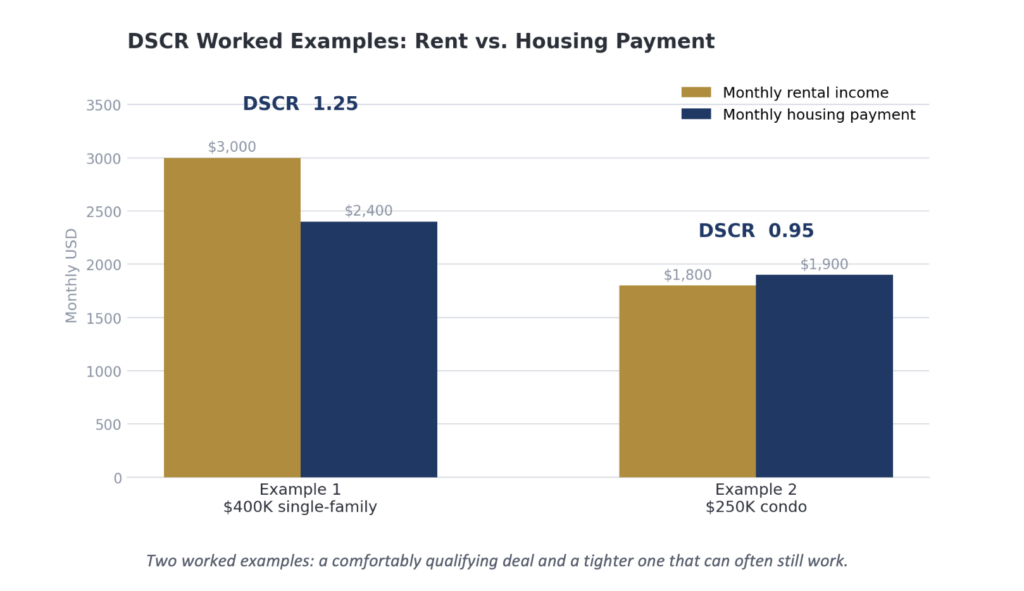
Example 1: A straightforward qualifying deal
The rental cost for the single-family home is $400,000, with a total monthly rent of $3,000. The monthly cash flow is $2,400 in total, consisting of principal, interest, taxes, and insurance. The DSCR would then be calculated as $3,000 ÷ $2,400, equalling 1.25. This number is above what most lenders would consider as their minimum requirement. Personal tax returns or pay stubs may not be necessary.
Example 2: A tighter deal that can still work
The cost of the property is $250,000, and it is earning $1,800 in rent. The total payment is $1,900 per month. The DSCR ratio is $1,800 ÷ $1,900 = 0.95. This is below 1.00, meaning that the rent is not covering the payment fully. General lenders may reject the loan, but there could be a specific DSCR program offering loans.
Foreign nationals do not need to translate foreign payslips. FEIE tax returns may not need scrutiny. DTI may not determine the qualifications of expats.
11. Buying a Home, Vacation Home, or Investment Property Overseas
There are various reasons why an American expat would decide to purchase property. For instance, this could be done as an investment property, vacation home, secondary home, and others. Some expats may purchase property to have a permanent home or a home for the kids while they pursue their university education. Others buy property for the first time so that it becomes part of their growing investment portfolio. In order to determine the appropriate loan structure, one should take into consideration the purpose of buying this property.
A property’s intended use should never be represented differently than it actually is simply to obtain more favorable financing.
The mortgage structure has to match the actual, intended occupancy.
The conventional loan underwriting process may not be the most ideal for investments. DSCR lending provides a much easier and faster process.
ILLUSTRATIVE EXAMPLE
Rachel Kim — Seoul, South Korea
Rachel, based in Seoul, wanted a short-term rental property in Scottsdale, Arizona — clearly an investment, not a home she’d occupy. Representing it as a second home might have looked like an easier path to approval, but it would have misstated the property’s actual use.
Qualifying it correctly as an investment property under DSCR, based on projected short-term rental income, turned out to be simpler anyway — no personal income documentation needed, and no risk of an occupancy misrepresentation surfacing later in underwriting or after closing.
12. Already Own U.S. Real Estate? Cash-Out Refinancing and Equity Recycling
For those expatriates who already have investments in the form of U.S. properties, their existing real estate can be used to finance their further activities. This could mean either refinancing at a reduced rate or drawing on equity.
Worked example: releasing equity
| Item | Amount |
| Current property value | $1,500,000 |
| Existing mortgage balance | $400,000 |
| Current equity | $1,100,000 |
| New loan at 80% LTV (illustrative) | $1,200,000 |
| Less existing mortgage payoff | −$400,000 |
| Potential gross cash-out | $800,000 |
The freed up capital can be used for paying off the down payment for another real estate. The capital can also be used for renovation purposes or for diversifying the portfolio. There might be other approved uses as well. The maximum amount that can be raised will depend on the loan product and property type.
Equity recycling: turning one property into two
The above process is used by some investors as an ongoing investment strategy instead of a one-off transaction. They buy an asset and let it appreciate in value. They will then refinance and extract some money from it. This money may be used as the down payment for another investment. The process will therefore continue in a repetitive manner. One investment can eventually be used as the backbone of other investments. Nevertheless, the process involves higher risks because there is more leverage.
Refinancing isn’t only about cash-out
There is no requirement of taking out any money in a rate-and-term refinance since the interest rates may have changed since the time of the first loan. Also, the individual’s creditworthiness may have improved in the meantime. Another possibility is that credit worthiness in the US may have been restored after being away from it for some time.
ILLUSTRATIVE EXAMPLE
Daniel Osei — Accra, Ghana
Daniel owned a fully-tenanted Texas rental purchased six years earlier. Rather than saving from scratch for his next property, he refinanced the Texas property, releasing a portion of its accumulated equity.
That released capital became the down payment on a duplex in Ohio, purchased under a DSCR loan qualified on the new property’s own rental income. Two properties, funded from what started as one — with the obvious trade-off of now carrying debt service on both.
13. Building a Portfolio: Is There a Limit?
A common misconception is that an expat can only carry one financed U.S. property at a time. That isn’t accurate.
Fannie Mae is limited to up to 10 financed one-to-four unit residences per the agency’s requirement. This limit applies to some types of second homes and investment properties. The limit is inclusive of the mortgaged principal residence. Other automated underwriting requirements also apply. Breaching the above limit usually excludes conventional agency financing as an option.
DSCR financing and portfolio loans evaluate properties from the rental standpoint. It is not subject to the same limit of financed properties. This can be advantageous for those who intend to purchase larger property portfolios.
ILLUSTRATIVE EXAMPLE
Priya Nair — Bangalore, India
Priya, an American expat working in Bangalore, bought her first U.S. rental five years ago. Rather than buying one property at a time with no broader plan, she used each property’s seasoning and appreciation to refinance and fund the next purchase under DSCR financing.
She now holds five financed rental properties — a scale that would have run into conventional agency limits far sooner, but which DSCR’s per-property underwriting accommodated without issue.
14. Moving Back to the U.S.: Why Timing Matters
If you expect to be able to return to the U.S, initiate the discussion about the mortgage prior to moving. This is true regardless of whether your move is still uncertain.
Your mortgage profile could undergo significant changes at the point of repatriation. Your foreign employment could come to an end with the commencement of U.S. employment. Foreign income might no longer be relevant on the mortgage application. Your housing expenses could change in the process as well. You could need to build a new credit history in the U.S. as well. Pre-approving yourself three to six months ahead of time would give you some additional time to plan.
ILLUSTRATIVE EXAMPLE
Alan Whitfield — Abu Dhabi to Denver
Alan knew his assignment in Abu Dhabi would end in roughly a year, with a return to Denver already planned. Rather than waiting until he landed, he got pre-approved four months before the move, while his U.A.E. income and employment history were still current and easy to document.
By the time he arrived in Denver, his financing was already in place. He closed on a home within three weeks of landing — well ahead of buyers who started their financing conversation only after relocating.
15. The U.S. Expat Property-Buying Process, Step by Step
- Get pre-approved first. Determine which loan program, budget, and documentation requirements you have before you start searching.
- Determine the purpose of the property. Decide whether you will make it your main residence, second home, or investment property. The purpose determines your mortgage program and DTI.
- Select the right property. Think about the location, price, and eligibility for financing. In the case of investments, analyze demand on rentals and property management issues.
- Deal with an experienced agent. Try to find an agent who knows how to work with overseas buyers. Video tours, virtual inspections, and remote workflow should be common practice.
- Make an offer with financing in place. Pre-approval can help you make an offer. It also proves that your financing is already under way.
- Finish with underwriting and documentation. Lenders check income, assets, credit, property, insurance, title, and funds. Specialist lender helps in expat file management.
- Complete closing remotely. Most expats close deals without coming back to the U.S. Remote Online Notarization and mobile notary services may be used. Requirements differ by state, lender, and title company.
If your money is in foreign currency, make sure to have a discussion about the FX timing with your lending institution early on. Ensure there is ample time for the transfer of funds from overseas before closing because exchange rates can fluctuate prior to closing.
ILLUSTRATIVE EXAMPLE
Nadia Hassan — Doha to Orlando
Nadia, based in Doha, found an Orlando investment property through an agent experienced with overseas buyers who’d already built a routine of video walkthroughs and virtual inspections for remote clients like her.
With pre-approval already in hand, she made a competitive offer, moved through underwriting with documentation her lender already knew how to evaluate, and closed using Remote Online Notarization — without a single trip back to the U.S.
16. Real Estate Bridge Loans
A bridge loan is an example of short-term finance that is collateralized. It is used to overcome a time issue rather than compete with a 30-year mortgage on a cost basis. In case of expatriate investments, bridge financing can be used in a number of cases including the following:
- Buying before selling the right property surfaces before another property has closed.
- A competitive, fast-close acquisition a seller wants to close in ten days, well inside a conventional underwriting timeline.
- Renovation or repositioning, the property needs substantial work before it can qualify for conventional or DSCR financing.
- A property or borrower that doesn’t fit conventional underwriting at all.
- Bridging a 1031 exchange timeline, where funds need to move before permanent financing can be arranged.
- Recapitalizing part of an existing portfolio quickly to fund the next acquisition.
Worked example: speed over rate
The property is priced at $5,000,000 and it is currently under contract for $4,500,000. Closing on this deal is required within ten days. This is significantly less time than what is usually taken in a normal mortgage loan process. The buyer has plenty of money but doesn’t wish to liquidate any investment. By providing the borrower with a 70% LTV bridge loan, one could get $3,150,000 to buy the property. The rest of the money will be supplied by the borrower.
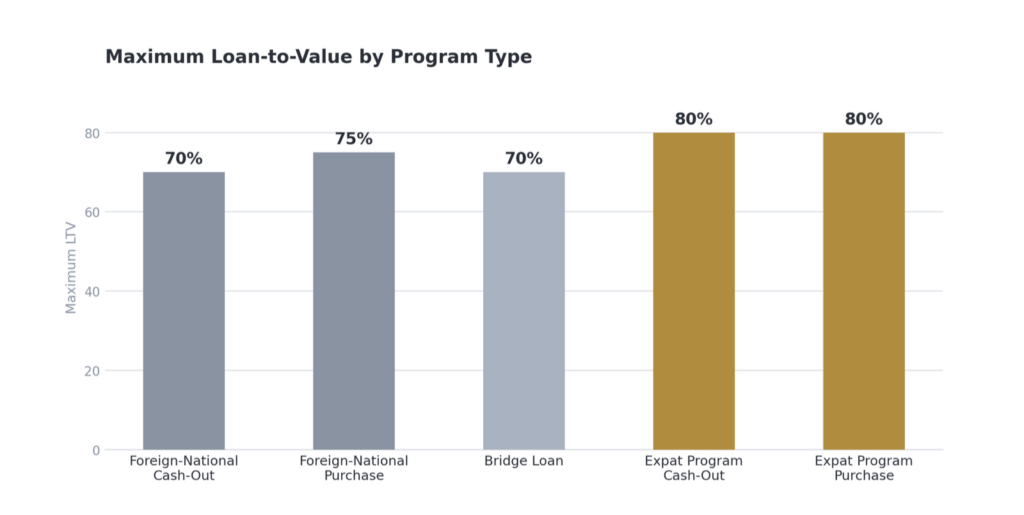
Illustrative maximum LTV by program type. Actual terms vary by borrower, property, and lender.
Typical bridge loan parameters
| Parameter | Typical Range |
| Minimum loan amount | $1,000,000+ |
| Maximum LTV | Up to 70% |
| Rate | Approximately 10–12% |
| Origination fees | Approximately 1–2 points |
| Closing timeline | As fast as 10 days |
| Term | Typically 1–2 years |
Bridge loans are made possible by two components; these being capital and underwriting. The lender should have committed capital that is deployable. Bridge loaning can be quickened by having direct access to capital. It will also help eliminate delays caused by third party warehouse lenders. The above mentioned terms are just illustrations.
ILLUSTRATIVE EXAMPLE
Jonathan Harris — Toronto-based fund manager
Jonathan identified an off-market multifamily property in Georgia at a strong basis, but the seller wanted to close in twelve days — well outside any conventional or DSCR underwriting timeline.
A bridge loan closed in ten days against the property’s as-is value, securing the deal. Six months later, once the property was stabilized with tenants in place, Jonathan refinanced the bridge loan into permanent DSCR financing at a materially lower rate.
17. Common Reasons Expat Mortgages Get Declined
- The foreign income does not meet the lender’s documentation requirements. It may be strong; however, it won’t be verified properly by the lender.
- The foreign employer does not fill out a verification form. This usually happens to multinational companies that do not have a U.S. payroll system.
- There is no U.S. W-2. Some lending institutions focus on using W-2 for underwriting purposes.
- U.S. credit is thin or inactive. This usually takes place after years of minimal financial activity in the United States.
- The lender is unable to handle a foreign mailing address. Some lending systems are not equipped for foreign addresses.
- The tax return has information regarding FEIE or foreign tax credits. This may be read improperly and interpreted as insufficient income.
- You own several properties in the United States. Property limits of an agency may limit your financing options.
- The investment property is considered for conventional underwriting. DSCR or portfolio financing may be more appropriate for such a property.
- The property type does not match the programs offered by the lender. It can be a non-warrantable condo, vacation rental or small multifamily property.
- The lender does not specialize in expat files. In some cases, this may explain the entire challenge.
The majority of the above-mentioned problems relate to documentation and suitability of programs. This does not mean that they indicate lack of creditworthiness. With the appropriate financing company and loan arrangements, many of these problems could be overcome.
18. Why Specialization Matters
Consider a doctor treating 1000 people every year. There is a possibility that one of them will have an uncommon condition. But even then, he could refer that person to a specialist. A specialist would deal with such cases all the time. Experience in a narrow scope may give deeper insight into uncommon cases.
The same applies to mortgage loans. A general mortgage broker would deal with many loan applications per year. However, he may deal with very few U.S. expat applications. Limited exposure could complicate the process of verifying foreign income statements. The same holds true for foreign earned income exclusion and dormant credit history in the U.S. Specialists have experience with such borrower types. They may even be used to foreign employment and currencies, foreign residency, and expat credit. Foreign employment verification, DSCR, cash-out, portfolio lending, remote closing, and so forth would also be familiar to them.
ILLUSTRATIVE EXAMPLE
Denise Okafor — declined three times before finding the right fit
Denise, a consultant based in Lagos with U.S. citizenship, was declined by three different banks over four months — each for a different stated reason: foreign address, no W-2, thin credit file.
None of the three declines were really about her qualifications. Her fourth application, to a lender built specifically around this borrower profile, closed in under three weeks using the same income, the same credit history, and the same property — just read by underwriters who’d seen this exact file shape before.
19. The Expat Mortgage Documentation Checklist
Exact requirements vary by program, but an expat borrower should generally be prepared to gather some combination of the following:
| Category | Typical Documents |
| Identification | U.S. passport; Green Card or visa/residency documentation where applicable |
| Income | Employment contract or letter, payslips, foreign salary documentation, bonus or business income documentation |
| U.S. tax | Form 1040, Form 2555 where applicable, schedules, IRS transcripts where required |
| Assets | U.S. and foreign bank statements, brokerage statements, retirement and investment accounts |
| Credit | U.S. credit report; foreign credit documentation and an explanation of any inactive U.S. credit, where applicable |
| Existing real estate | Mortgage statements, property tax statements, leases, rental statements, insurance, HOA information |
Don’t assume a missing document automatically disqualifies you.
Ask a specialist what alternative documentation is acceptable under the specific program — there is very often more than one way to establish the same fact.
20. The U.S. Expat Mortgage Decision Tree
A useful way to think through which financing path fits your situation:
- Do you have active, recently-used U.S. credit? → Standard expat or conventional financing is likely available. If not, an international/foreign-national-style program is the more realistic starting point.
- Is the property an investment? → DSCR is generally worth evaluating first. If it’s for personal use, second-home or primary-residence underwriting applies instead.
- Are you planning to move back to the U.S.? → Start the pre-approval conversation before the move, not after.
- Do you already own U.S. real estate? → Weigh refinance and equity-release options against your next goal, whether that’s a lower rate or capital for the next purchase.
- Do you need capital quickly, ahead of a permanent-financing timeline? → Compare cash-out refinance, DSCR refinance, and bridge financing.
- Is the transaction unusually large or complex? → Portfolio, non-QM, or bridge financing are generally the more realistic starting points over a standard agency loan.
The aim is not only to maximize LTV. The lower headline rate cannot be the sole basis for the decision. One must take into account leverage, interest rate, and liquidity. Other things to think about include the use of this loan in future endeavors.
21. Where U.S. Expats Live — and Why U.S. Real Estate Still Wins
There is no consolidated government database that keeps track of precisely where all the Americans residing abroad live. Thus, these statistics offer an overall idea about where the American population resides. These numbers come from United Nations migration data.
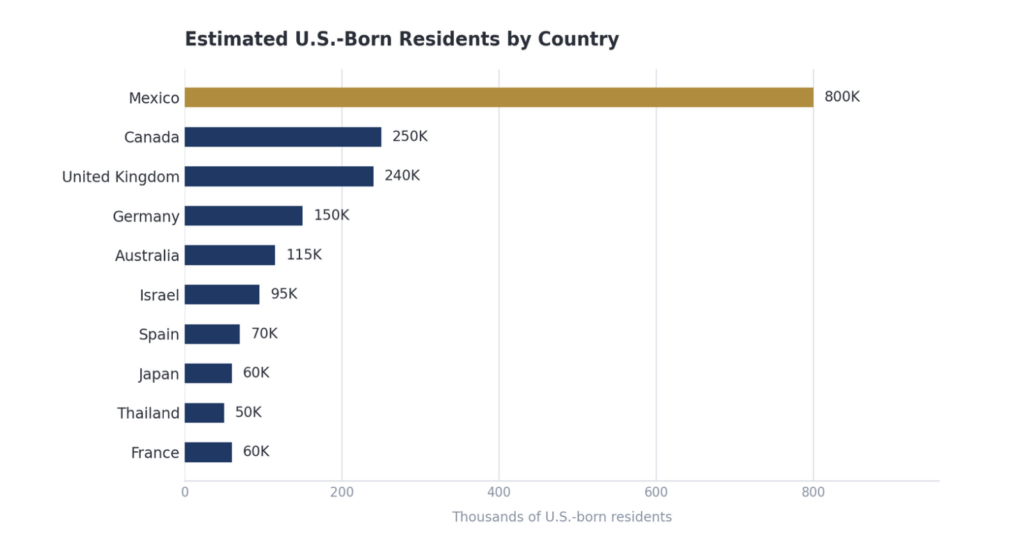
Estimated U.S.-born residents by country. Figures vary meaningfully by source and methodology.
But size is not the only significant variable. There are some other countries whose American population is smaller but financially more powerful. Singapore, UAE, Switzerland, Hong Kong, and the United Kingdom are prominent examples. Their population comprises wealthy people such as investors and entrepreneurs. Their population may not be bigger than that of Mexico or Canada.
The currency question
The money of the expatriate will usually be in a currency that is different from the American dollar. Examples of such currencies are Singapore dollars and British pounds. Some of the other currencies used include the euro, Australian dollars, and UAE dirhams. Buying property in America means that some of your wealth will now be in dollars. This could mean that you have also put yourself at risk financially in terms of liability in dollars. What matters here is not just the exchange rate today but what a 5%, 10%, or 15% difference might do to your investment.
Why U.S. real estate still wins the comparison
No matter where you hail from, the local money and property market will likely vary from your permanent financial base. Expatriates can have large sums of money outside their country of citizenship. Purchasing properties in the United States is like investing in dollars in a country with the legal system you know. There are title insurance and English-language paperwork to secure any purchase.
Foreign nationals spent about $45.3 billion on existing homes in the United States between April 2025 and March 2026. This figure was released by the National Association of REALTORS®. In the case of expatriates from America, there might be another story.
22. Buying a Home for Your Child’s College Years
Perhaps this is one of the most crucial sections for you as a parent. Most families have not thought seriously about this. In case your kid studies in a college in the U.S., accommodation charges can stretch to four years. The problem lies in the fact whether those charges vanish or have some possible value.
This is a decision that every expat family has to make. They either pay for the dormitory or rent from the owner. This way you are paying for something, but you are not building anything in the process. There is always another way out, though.
The core idea: your child’s rent becomes your mortgage payment
Most university townships have a regular supply of student tenants. Students require housing every year. There is constant demand for rentals in such a situation. Such demand would make the approach viable. You should not purchase a studio for your kid. You should buy a larger property in proximity to the university. Such a three or four-bedroom home can generate additional revenues. Your kid will use one room, while the other bedrooms could be rented out by other students.
The basic math:
A property with 3–4 bedrooms, purchased near a university, can generate enough roommate rental income to offset a large share of the monthly mortgage payment — while your child lives there rent-free or at reduced cost, and you build equity in a property you own rather than paying a landlord who builds equity in one they own.
A worked example
Let’s take an example of a $450,000 four-bedroom house near a major public university. The 20 percent down payment will be $90,000 and the balance of $360,000 can be mortgaged. The monthly payment will come out to be about $2,700, which covers principal, interest, taxes, and insurance. Your child stays in one bedroom, while the rest of the three rooms are rented out by your child’s classmates.
| Item | Monthly Amount |
| Total mortgage payment (PITI) | $2,700 |
| Roommate rental income (3 bedrooms × $650) | −$1,950 |
| Net monthly cost to the parent | $750 |
Having a net carrying cost of around $750 per month is much less expensive than renting even just one dorm room. In contrast to paying rent, the $750 goes into paying back the loan used to purchase a valuable asset that is yours.
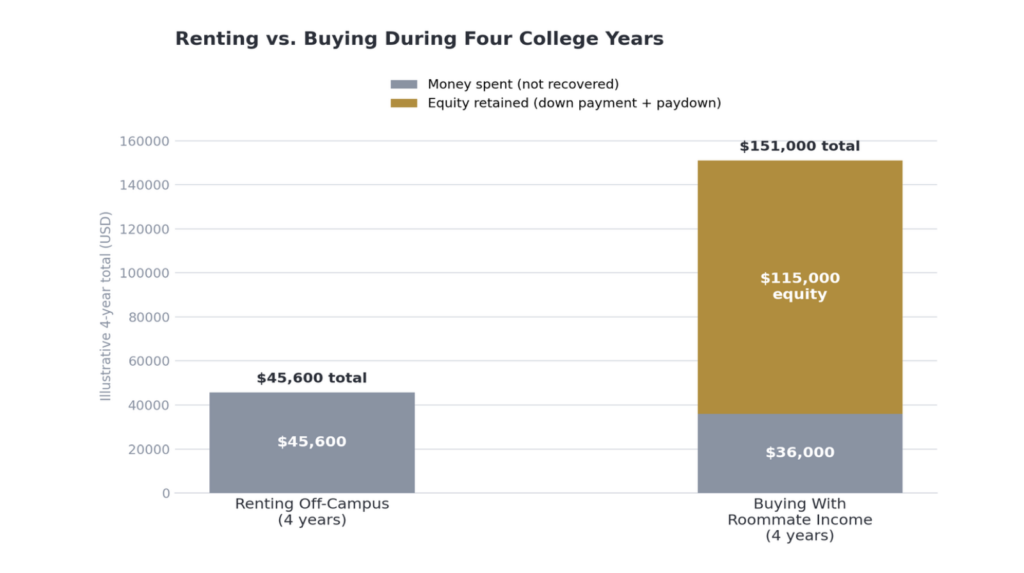
Illustrative four-year comparison. Actual rent levels, mortgage terms, and property values vary by market.
23. Why this can be one of the more persuasive decisions in this entire guide
1. The roommates effectively subsidize your child’s housing
This is how the strategy works. You are not only buying a home for your kid; you are actually buying a house that produces money and gives your kid a place to stay. The rents earned from the rest of the rooms will pay off the mortgage. The earning of money is the core of this strategy.
2. Capital appreciation can offset — or fully recoup — a meaningful share of the cost
With towns of universities having low housing stock, constant demand from students can exist. In the past, certain housing markets may have also shown increasing value over periods of extended ownership. For instance, think about a house valued at $450,000 over a period of four years. Some value appreciation could be possible to recoup at least some of the total ownership expenses. Good value appreciation could help in recovering a higher percentage of the expenses. However, value appreciation can never be guaranteed. Values can also stay flat or decrease. Costs associated with buying and selling will also cut into your profits.
3. A head start after graduation
The property need not be sold upon graduation of the child. It can be used as the first property by the child as an independent young professional. In case the child moves out, the property can be retained as a rental property. It will help in earning rental income from the property. Alternatively, the property may be sold and the proceeds of sale shared with the child. The money earned will help in purchasing the next property.
4. Potential tax advantages — with an important nuance
As a portion of the property is rented out for real use, some expenditures may be eligible for deduction from rental income. The rooms will be lived in by paying roommates who are not related to each other. Possible deductions could be mortgage interest, property tax, insurance, depreciation, and maintenance expenses. Such deductions might be relevant to other rental property as well.
The nuance worth understanding before you count on this:
The IRS treats a dwelling unit used personally by you or a close relative differently from a straightforward rental property. If your child lives in a bedroom rent-free, that portion of the property is generally treated as personal use rather than rental use, which can limit how much of the property’s expenses are deductible against the rental income from the other rooms. The rules here turn on the specific facts — how many days of personal use occur, whether your child pays fair-market rent for their own room, and how the arrangement is structured — and get technical quickly. This is a conversation for a qualified tax professional before you buy, not an assumption to build the whole plan around.
How this typically gets financed
Since the purpose of this property will be two-fold, it may not be easy to determine which type of loan would suit this purpose. Your child can reside in the property whereas your friends rent out the place. As per the nature of the property, it can come under the second-home category. For more information regarding DTI treatment, refer to section 9. In case of the predominant use of the property for rentals, it may be considered as investment property.
ILLUSTRATIVE EXAMPLE
The Whitfield Family — London to Chapel Hill
The Whitfields, U.S. expats based in London, faced the standard choice as their daughter prepared to start a four-year degree: pay roughly $1,100/month for an off-campus apartment, or buy something.
They purchased a four-bedroom house near campus for $420,000 with 20% down. Their daughter took one room; three classmates rented the others at $650 each, covering nearly all of the $2,550 monthly mortgage payment and leaving the family a net cost of well under $200 a month — less than a tenth of what four years of straightforward rent would have cost.
When their daughter graduated, the local market had appreciated modestly. They sold the property, and the proceeds — after paying off the remaining loan balance and transaction costs — covered a meaningful share of what they’d spent on her final two years of tuition. Market conditions vary, and a similar outcome isn’t guaranteed in every city or year — but renting alone would have guaranteed the opposite: zero dollars recovered, regardless of the market.
That does not necessarily imply that you should view the period when your kid goes through college as primarily an opportunity for investing money. Your primary concern will remain the provision of a suitable place to stay. But it would help if you compared the expenses before making a decision on leasing. Four years’ worth of rental fees might prove to be quite costly. Investing might present the chance to recover part of your expenditure.
24. Frequently Asked Questions
Q1: Can a U.S. citizen living overseas get a U.S. mortgage?
Yes, there are several different mortgage programs that apply to Americans abroad in the U.S. eligibility is based on income, credit, assets, residency, and loan type. Requirements of programs also limit the types of programs available. Finding a specialty lender who focuses on expats can be a good place to start.
Q2: Do I need to live in the U.S. to get a U.S. mortgage?
No, there are several programs available to borrowers who live abroad including American citizens living abroad, Green card holders, and foreigners buying U.S. property.
Q3: Why do banks keep declining my mortgage application as a U.S. expat?
Declines typically happen because of program fit and not credit issues. A foreign mailing address is going to make things difficult for you. Foreign income does not have a W-2. Additional tax form analysis might be required. The absence of a credit file in the United States is also an issue.
Q4: Do I need a W-2 to qualify for a U.S. mortgage as an expat?
Expatriate-specific income verification programs will be able to prove the amount of income earned overseas via alternative documents. This can include letters from the employer, pay slips overseas, account statements, and tax documents. Foreign employers usually do not provide W-2 forms. Hence, the bank needs another way of proving income.
Q5: Does the Foreign Earned Income Exclusion (FEIE) hurt my mortgage application?
The FEIE helps you to lower the amount of income you earn. This might lead to the lender not knowing your qualifying income, especially when the lender is not experienced. The specialty lender can help you assess the gross foreign earnings and prove your income through the tax papers.
Q6: Do I still need to file U.S. taxes as an expat even if I owe nothing?
Yes, citizens of the U.S. of America and Green Card holders normally file their annual U.S. tax returns. This includes situations where the FEIE makes their tax burden zero. Such consistent filings will assist the lending institutions when assessing the income of the applicant for the purposes of mortgage underwriting.
Q7: What is a DSCR loan and how does it work for expats?
A DSCR loan evaluates the viability of an investment property from the rental income that is being earned from the property. It does not normally depend on the employment income of the individual. It looks at the monthly rental income versus monthly debt payment. A ratio of 1.00 or above is preferred by many programs. Some lenders will go for those below 1.00. However, the conditions for those will be different depending on the loan program.
Q8: Can an expat get a DSCR loan through an LLC?
Potentially, yes. Certain mortgage programs give the opportunity for the borrower to buy using LLC. However, this is normally determined by the lender and the state where you intend to buy the property. You should inquire about this from your lender. It depends on the financial condition of the borrower and the property itself. There may be better alternatives.
Q9: Is DSCR always better than a conventional mortgage for an expat?
Not necessarily. It all depends on the financial profile of the borrower and the property. U.S. income and good credit might support conventional loans. Complex income or rental income cash flow might support DSCR financing.
Q10: What credit score do I need for a U.S. expat mortgage?
The requirements may differ from one program to another. But documented borrowers who have good U.S. credit should qualify. Borrowers who do not have active U.S. credit might still qualify on foreign-national terms. This can result in lower leverage.
Q11: What’s the maximum loan-to-value (LTV) for a U.S. expat mortgage?
The maximum LTV will depend on the occupancy, property type, loan amount, and credit. This can also depend on whether the loan is an agency loan or non-QM. In some specialized expatriate programs, the maximum LTV could go up to 80% for qualifying properties. Borrowers who don’t have active U.S. credit might get lower leverage. With foreign-national terms, it might be capped at about 75% LTV.
Q12: How is DTI calculated for a U.S. expat buying an investment property?
For almost all DSCR investments, the personal debt-to-income ratio does not come into play. The main consideration here is whether the rental income can cover the property debts.
Q13: How is DTI calculated for a U.S. expat buying a vacation or second home?
Lenders will usually include your existing housing expenses in the total cost of the new United States real estate. This amount will be compared to your monthly gross income. The ideal ratio is around 43%. But this is not a constant as it will vary depending on the mortgage program and method of underwriting.
Q14: Can I get a mortgage if I only have a Green Card, not U.S. citizenship?
Potentially, yes. Eligible legal permanent residents can get funding from Fannie Mae. The conditions could be on par with those for American citizens. Rules will apply, of course.
Q15: Should I get pre-approved before moving back to the U.S.?
Generally yes, begin preparing three to six months ahead of time. Begin preparations earlier if you have an unusual income or credit status. That will allow the lenders enough time to evaluate your paperwork.
Q16: Why does maintaining U.S. credit matter if I live abroad?
U.S. credit record can become dormant after about 12 to 24 months. That could impact your future financing options and prices. Maintaining one or two U.S. credit cards would help.
Q17: What happens if I’ve been abroad so long I no longer have a usable U.S. credit file?
The borrowers could become eligible under the international or foreign national program. The program can feature lower maximum LTV and higher interest rates. Proper loan payments can establish a viable U.S. credit score. Refinancing can become possible later on.
Q18: Is there a limit to how many U.S. properties an expat can finance?
Up to 10 financed one-to-four unit properties are allowed by Fannie Mae per borrower. Automated underwriting requirements and other terms still apply. Portfolio and DSCR programs often have separate requirements. Individual property analysis is based on its performance. Thus, the numeric requirement mentioned above will not necessarily apply.
Q19: What is a real estate bridge loan and when do expats use one?
A bridge loan serves as a short-term financing instrument based on the asset. It might be used for funding of improvements or time gap filling. 1031 exchanges could also require such a solution. Repayment typically takes from one to two years. Bridge financing solutions might be preferred by expat investors who need flexibility and speed. However, this financing option might be more expensive than traditional financing.
Q20: Can foreign-earned income be used to qualify for a jumbo mortgage?
Potentially yes, expatriate or non-QM jumbo programs might accept foreign income documents as well. Those could include employer letters, paystubs, bank statements, etc.
Q21: Can I close on a U.S. property while still living overseas?
Also, remote closing could be possible in many cases. Remote closing solutions could include remote online notarization or mobile notary services. Availability of those options depends on state regulations, title agents, and lenders’ policies.
25. About This Guide
This guide is an independent educational resource for American expats. It provides detailed information on the mortgage funding offered by the United States to foreigners. This resource was compiled using underwriting expertise provided by America Mortgages. America Mortgages is the U.S. mortgage division of Global Mortgage Group. This mortgage company provides mortgages to American expats, Green Card holders, and foreign investors of U.S. property.
All numbers and rules cited above are based on general industry standards at the time of publishing. They are for educational purposes only. The information in this guide is not intended to offer tax, legal, investment, or financial advice. This is not an offer to lend. Terms of mortgages such as interest rates, loan-to-value, mortgage amounts, and mortgage terms are different for each program. There are other requirements for mortgages that will depend on the property, the applicant, and the state.
It is wise to start considering financing even before locating the desired property. One should not take for granted that the decision of one lender reflects the U.S. mortgage market. The circumstances under which your financing needs arise could include U.S. citizenship, living abroad, having foreign income, U.S. taxes, credit, and real estate.

